Performance Financial Overview
The past year was a powerful demonstration of what the ADCB Group can accomplish with a clear strategy, a robust governance framework, and close collaboration. This financial overview is part of that demonstration, reflecting our adherence to financial discipline and a prudent approach to risk management.
The figures and charts that feature in the following pages provide a more detailed insight into our financial performance this year. These results are based on the full year pro forma financial statements for the combined entity, following the merger between ADCB and UNB, and the subsequent acquisition of Al Hilal Bank on 1 May 2019.
The results show we are well-placed to grasp the opportunities we are seeing in a rapidly transforming UAE economy.
2019 Financial Highlights
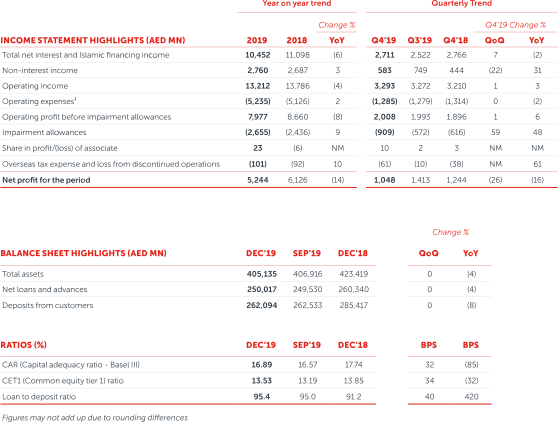
1 Operating expenses include non-recurring expenses pertaining to integration-related costs of AED 129 million in Q4’19, AED 107 million in Q3’19, AED 72 million in Q2’19, AED 38 million in Q1’19, and AED 46 million in Q4’18.
SOLID RETURN ON AVERAGE TANGIBLE EQUITY, IMPROVING COST OF FUNDS AND NET INTEREST MARGIN IN Q4’19
KEY INDICATORS
Return on average tangible equity
(ROATE %)2
Return on Average Assets
(ROAA %)2
2 For ROATE/ROAA calculations, net profit attributable to equity shareholders is considered, i.e. net profit after deducting interest expense on Tier I capital notes.
The Bank reported Q4’19 net profit of AED 1.048 billion and full year group net profit at AED 5.244 billion, with a double-digit annualised return on average tangible equity of 11.2%. Full year net profit, before one-off integration costs was 9% lower at AED 5.590 billion amid a soft operating environment, with improvements in operating expenses and higher non-interest income offset by higher cost of funds and impairment charges.
The one-off increase in Q4’19 impairment charges was primarily on account of a true-up on retail impairments post acquisition date after apportioning into fair value adjustments and impairment charges.
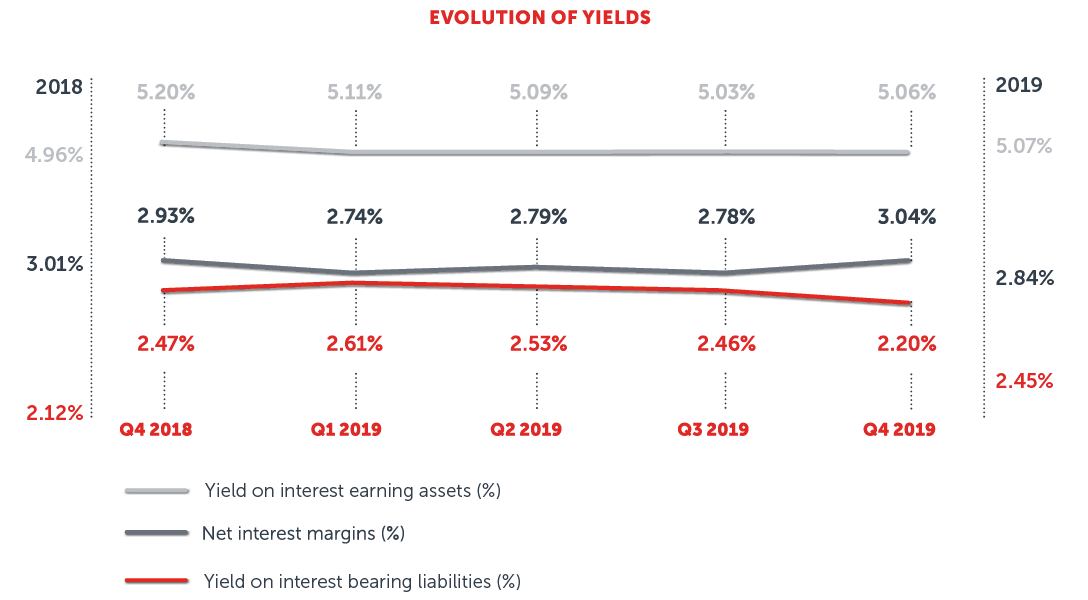
The Bank benefitted from a 41 basis point decrease in its cost of funds from Q1’19 to 2.20% in Q4’19. This improvement was primarily on account of the Bank’s strategy to grow CASA deposits and exit expensive time deposits, as well as declining benchmark rates. Consequently, net interest margin widened sequentially to 3.04% in Q4’19 from 2.78% in Q3’19, while net interest income increased by 7% on a quarterly basis to AED 2.711 billion in Q4’19.
Despite this improvement in the second half of 2019, cost of funds for the full year was higher than in 2018, due to higher volumes of deposits and higher benchmark rates in Q1’19 compared to Q2’19. This resulted in a 6% decrease in net interest income to AED 10.452 billion in 2019.
Full year non-interest income of AED 2.760 billion was up 3% year on year, largely due to a narrower revaluation loss on investment properties over 2018. Net fees and commission income was 4% lower at AED 1.996 billion, primarily attributable to lower loan processing fees. Trading income also decreased due to lower gains from foreign exchange and securities trading.
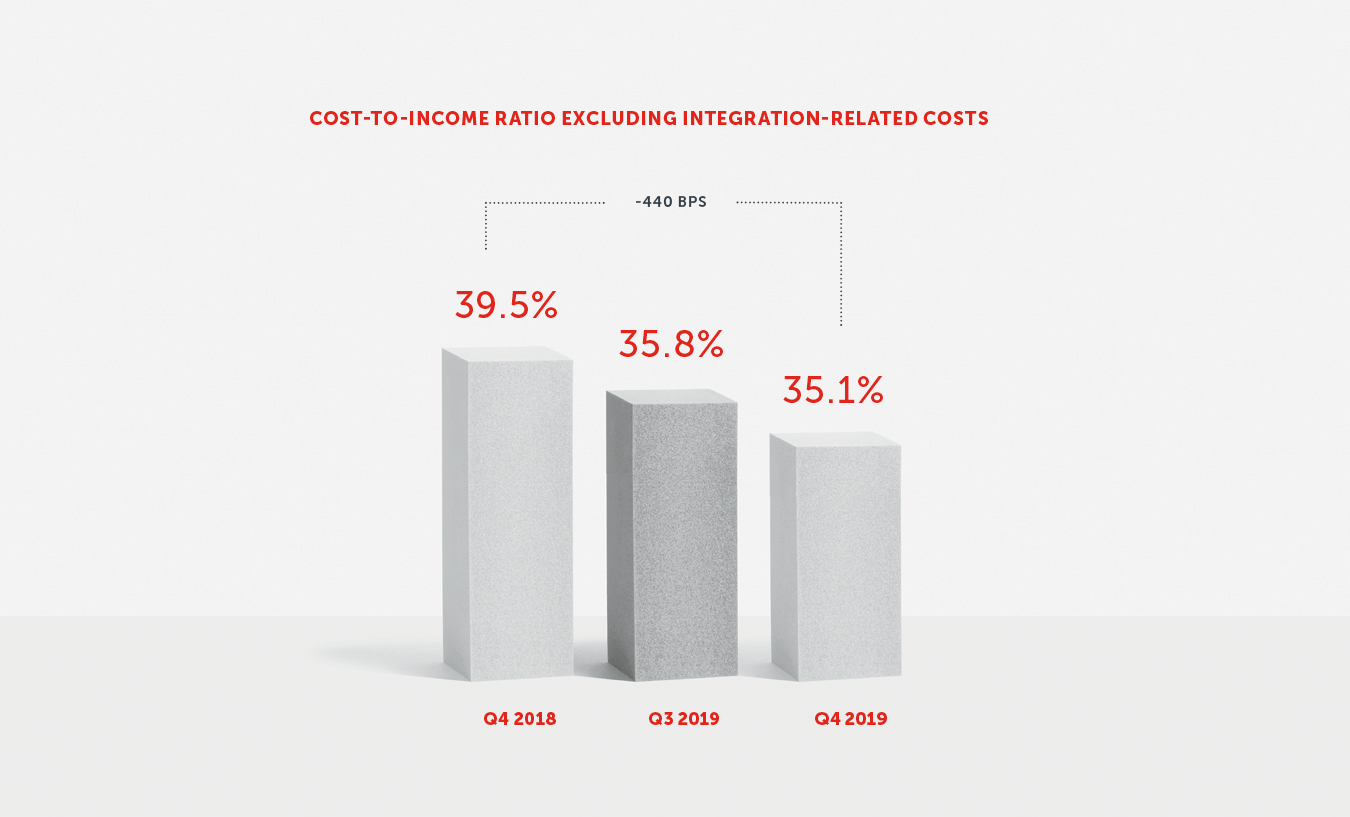
Q4‘19 results reflect the positive impact of the merger, with synergies and greater efficiencies resulting in a year-on-year decrease in operating expenses and a rise in operating profit. Operating expenses for Q4’19 were 2% lower year on year at AED 1.285 billion, and 9% lower when excluding one-off integration related costs. Cost to income ratio for the quarter, excluding integration-related costs, stood at 35.1% compared to 39.5% for the same period last year — an improvement of 440 basis points. Operating profit before impairment allowances increased by 6% to AED 2.008 billion year on year in Q4, and was up 10% when excluding integration-related costs.
In October 2019, the Group made an upward revision of run-rate synergy targets to AED 840 million, from the initial assessment of AED 615 million. The Bank has realised synergies of AED 350 million to date, while integration costs — at AED 346 million to date — are in line with the planned one-off integration expenditure of AED 980 million.
MERGER BENEFITS MATERIALISING THROUGH SUSTAINABLE REDUCTION OF COST BASE, Q4’19 COST TO INCOME RATIO IMPROVED
BASIS POINTS YEAR-ON-YEAR
RESILIENT BALANCE SHEET, SIGNIFICANT INCREASE IN LOW-COST CASA DEPOSITS
The Group’s balance sheet remains strong, with total assets standing at AED 405 billion as at 31 December 2019. Following the merger with Union National Bank and acquisition of Al Hilal Bank, the Bank is continuing with a comprehensive purchase price allocation (PPA) process, which is expected to be completed by the first quarter of 2020.
Net loans to customers were at AED 250 billion, a decline of 4% from 31 December 2018, mainly on account of a rise in corporate repayments and fair value adjustments. Total customer deposits decreased 8% to AED 262 billion, driven by the Bank’s strategic decision to exit expensive time deposits. Year-on-year, time deposits decreased by 16% to AED 160 billion, while CASA balances increased by AED 7 billion (8%) to AED 102 billion. CASA deposits comprised 39% of total customer deposits compared to 33.1% as at 31 December 2018.
As at 31 December 2019, the non-performing loan ratio (NPL) was 3.16%, while NPL ratio including net POCI (purchase or originated credit impaired) assets stood at 4.53%. Total impairment allowances were AED 10.464 billion, while the provision coverage ratio improved to 123.2%3 from 112.7% at the prior year end. Non-performing loans declined to AED 8.491 billion and net POCI assets (loans only) were AED 3.710 billion. As at 31 December 2019, cost of risk was 0.80%, compared to 0.74% a year earlier.
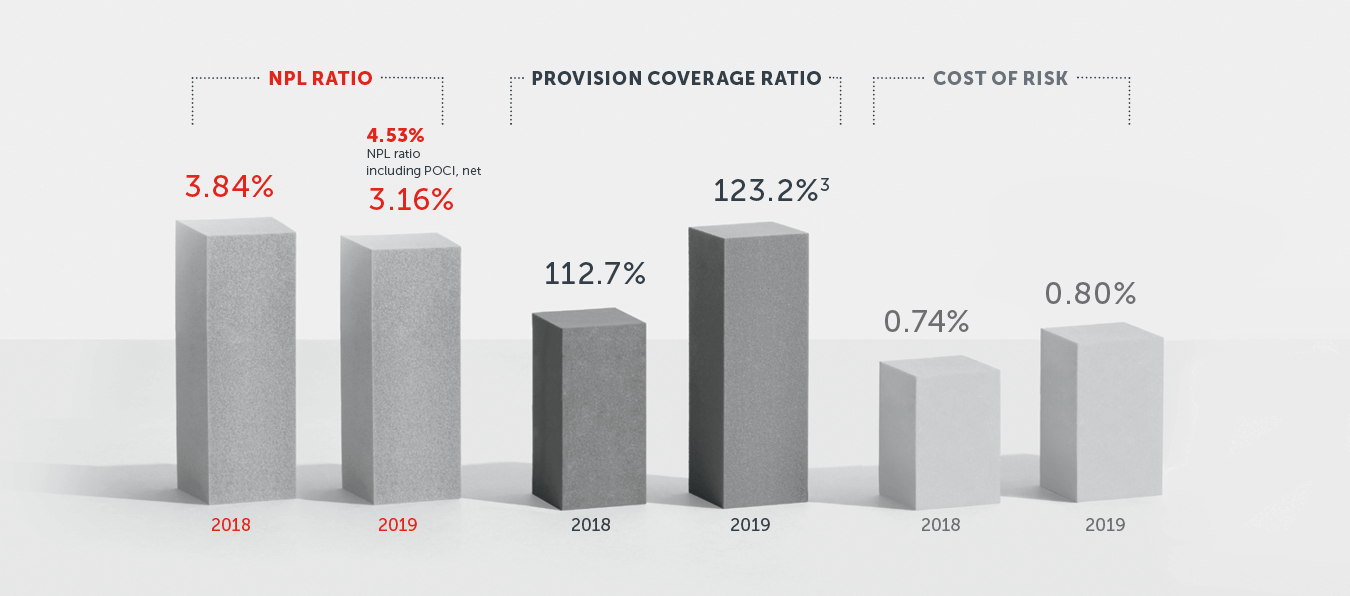
ROBUST LIQUIDITY POSITION, CAPITAL RATIOS COMFORTABLY ABOVE THE MINIMUM REGULATORY REQUIREMENTS
The Bank continues to maintain a comfortable liquidity position, with a liquidity coverage ratio of 127.3%, compared to a minimum ratio of 100% prescribed by the UAE Central Bank. The liquidity ratio was 26.1% and the Bank was a net lender of AED 10 billion in the interbank markets.
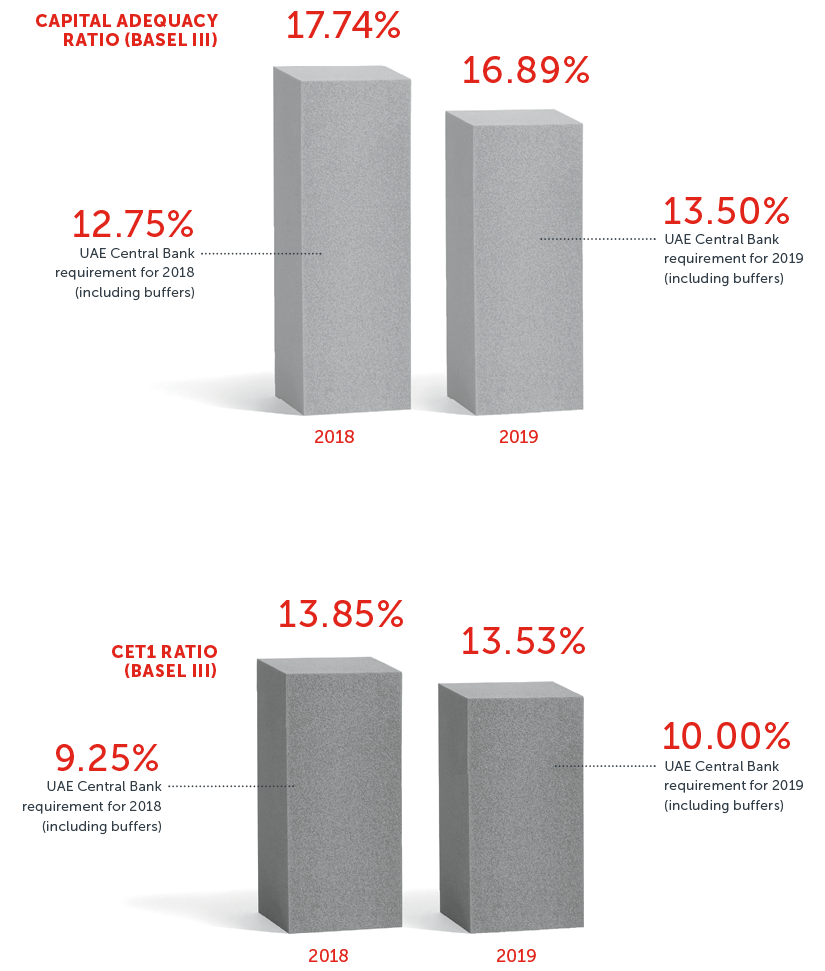
The Bank remains well capitalised with a Basel III capital adequacy ratio (CAR) of 16.89% and a common equity Tier 1 (CET1) ratio of 13.53%, comfortably above the minimum capital requirements of 13.50% and 10.00% respectively as prescribed by the UAE Central Bank (including buffers).
Recommended
Sustainability
ADCB Group is committed to managing the environmental and social impacts of its operations and promoting sustainable development in the UAE.
Economic Overview
The UAE continued to benefit from a stable and diversified economy with strong macroeconomic fundamentals, despite the lower growth environment.